Resume template · Updated October 2026
Risk analyst resume template
Short answer
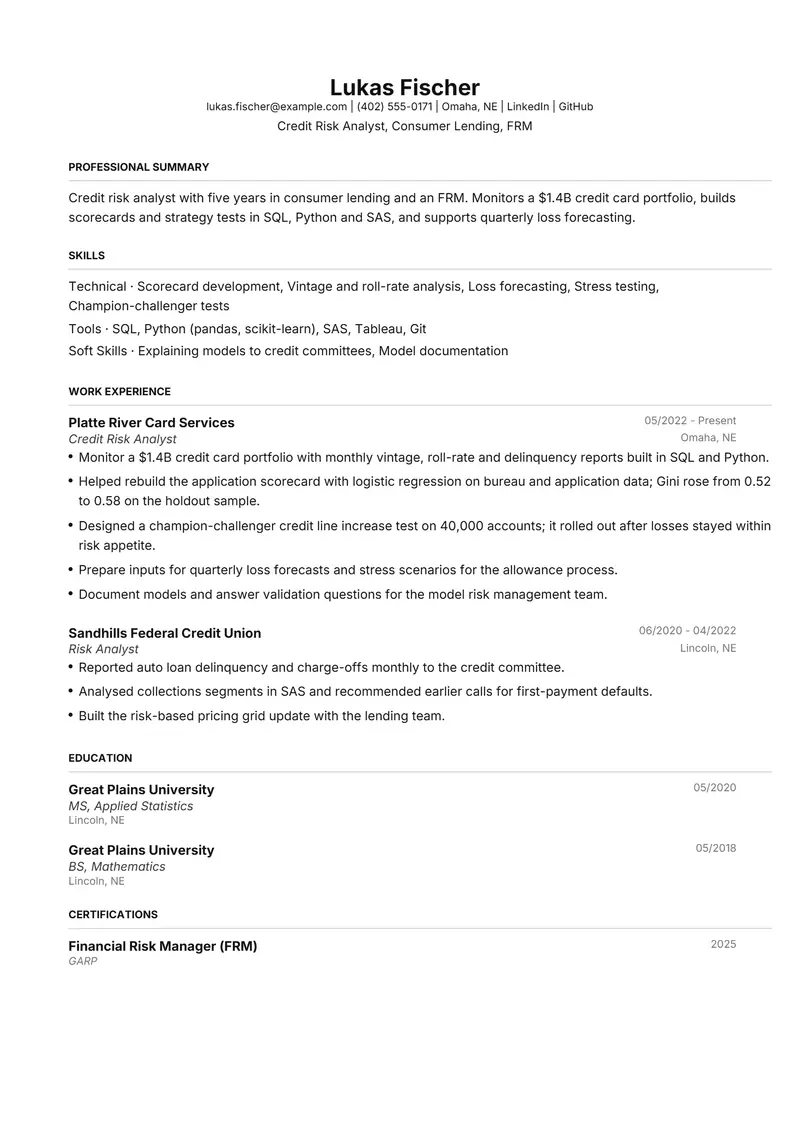
FAANGPath suits a risk analyst because the job is screened on technical skills: SQL, Python, SAS and modelling methods print in labelled rows before the jobs. The fictional sample monitors a credit card portfolio, helped rebuild an application scorecard, ran a credit line test that rolled out and supports loss forecasting, after starting in auto loan risk at a credit union. He holds the FRM.
Download the risk analyst sample
Lukas is a fictional credit risk analyst. Replace every detail with your own before you send it.
The files are made in your browser by Resumity's own exporters, from this sample. The builder opens it as your own resume: click any line to replace it. Free plan, no watermark.
Why FAANGPath suits a risk analyst resume
FAANGPath was designed for technical candidates and prints labelled skill rows above experience on a centred black-and-grey page. Risk teams screen on languages and methods (SQL, Python, SAS, logistic regression, vintage analysis), so showing them first answers the screening question before the first job.
Second choice: Meridian. Meridian keeps skills first with grey rules beside each heading; equally suitable for banks with conservative tastes.
What goes in each section, in FAANGPath's order
FAANGPath prints its sections in a fixed order, the same in the PDF and the Word file. Here is that order for this sample, and what to put in each section.
- Professional Summary. Risk type (credit, market, operational, model), portfolio or business size, years and your main methods. Add FRM or another credential in this sentence because certifications print near the end.
- Skills. Technical holds methods: scorecards, vintage and roll-rate analysis, loss forecasting, stress testing, champion-challenger testing. Tools holds languages and platforms. FAANGPath puts a dot after each label, so short items read best.
- Work Experience. Portfolio size, what you monitor, models you built or validated with one performance figure, and a strategy change your analysis drove. Mention model documentation for validators; it shows you work within governance.
- Education. Quantitative degrees (statistics, mathematics, economics, finance) on one line each, master's first.
- Certifications. Financial Risk Manager (FRM) from GARP with the year, or progress in the exams if you are partway.
The sample resume as text
The same content as the files above, so you can copy a line or compare it with your own.
Lukas Fischer
Credit Risk Analyst, Consumer Lending, FRM
Omaha, NE | lukas.fischer@example.com | (402) 555-0171 | linkedin.com/in/sample-lukas-fischer | github.com/sample-lukas-fischer
Credit risk analyst with five years in consumer lending and an FRM. Monitors a $1.4B credit card portfolio, builds scorecards and strategy tests in SQL, Python and SAS, and supports quarterly loss forecasting.
Experience
Credit Risk Analyst, Platte River Card Services, Omaha, NE (05/2022 to Present)
- Monitor a $1.4B credit card portfolio with monthly vintage, roll-rate and delinquency reports built in SQL and Python.
- Helped rebuild the application scorecard with logistic regression on bureau and application data; Gini rose from 0.52 to 0.58 on the holdout sample.
- Designed a champion-challenger credit line increase test on 40,000 accounts; it rolled out after losses stayed within risk appetite.
- Prepare inputs for quarterly loss forecasts and stress scenarios for the allowance process.
- Document models and answer validation questions for the model risk management team.
Risk Analyst, Sandhills Federal Credit Union, Lincoln, NE (06/2020 to 04/2022)
- Reported auto loan delinquency and charge-offs monthly to the credit committee.
- Analysed collections segments in SAS and recommended earlier calls for first-payment defaults.
- Built the risk-based pricing grid update with the lending team.
Education
MS, Applied Statistics, Great Plains University (05/2020)
BS, Mathematics, Great Plains University (05/2018)
Certifications
- Financial Risk Manager (FRM), GARP (2025)
Skills
Scorecard development, Vintage and roll-rate analysis, Loss forecasting, Stress testing, Champion-challenger tests, SQL, Python (pandas, scikit-learn), SAS, Tableau, Git, Explaining models to credit committees, Model documentation
How to make the sample yours
Name your risk type first
Credit, market, liquidity, operational and model risk need different skills. Put yours in the headline and drop terms from other areas.
Explain model results for non-specialists
Pair a statistic with its effect: "Gini from 0.52 to 0.58 on holdout, approving more good applicants at the same loss rate".
Show a strategy you changed
A credit line test, a cut-off change, a collections segment. Decisions that reached customers show business impact.
Mention governance
Model documentation, validation findings resolved, policy limits. Banks and lenders value analysts who make validation easy.
Match the tools in the posting
Some lenders still run SAS, others Python or R, and almost all use SQL. List the ones you can use in a technical interview.
Keywords to keep where they are true
Terms this kind of resume is usually searched for. Use the posting's exact wording, and only for work you have done.
- credit risk
- risk analysis
- portfolio monitoring
- scorecard development
- logistic regression
- vintage analysis
- roll rates
- loss forecasting
- stress testing
- champion-challenger testing
- SQL
- Python
- SAS
- FRM
Mistakes to avoid
- Model statistics with no business meaning attached.
- Mixing credit, market and operational risk jargon so the reader cannot tell what you do.
- Sharing loss rates or portfolio figures your employer treats as confidential; round or make them relative.
- Listing methods you have not used on real data.
How the sample PDF reads in text extractors
We exported this sample with Resumity's PDF exporter in Chrome on 2026-10-29 and read the file back with three open-source text extractors. This shows whether software that turns a PDF into text can recover it; it is not a test of any commercial applicant tracking system. How we test templates.
| Extractor | Name, email, phone | Headings | Bullets intact |
|---|---|---|---|
| pdf.js 4.10.38 | All found | 5 of 5 | 8 of 8 |
| pdftotext (Xpdf) 4.00 | All found | 5 of 5 | 8 of 8 |
| pypdf 6.13.0 | All found | 5 of 5 | 8 of 8 |
Frequently asked questions
How does a credit risk resume differ from a market or operational risk resume?
Credit risk resumes show portfolio monitoring, scorecards, loss forecasting and lending strategy. Market risk resumes show VaR, sensitivities and trading limits; operational risk resumes show risk and control assessments, incidents and key risk indicators. Use the vocabulary of the one you do.
Is the FRM worth listing?
For many risk roles, yes. GARP describes two multiple-choice exams and at least two years of relevant work experience for certification, so it shows both knowledge and time in the field. List exam progress plainly if you have passed only Part I.
How do I present model metrics to non-technical readers?
Give the statistic and what it changed: more approvals at the same loss rate, earlier detection of delinquencies, fewer manual reviews. Hiring managers outside modelling teams read the effect.
Should I list SAS if my team moved to Python?
Yes, if you can still use it; many banks run both. Put the language you use most first.
How do I show impact when risk work prevents losses rather than earning money?
Show the decision and its result: a test rolled out within appetite, a segment tightened before losses rose, a validation passed without findings.
Will applicant tracking systems read this FAANGPath PDF?
The sample PDF read back with its contact details, all 5 section headings and all 8 bullets intact in three open-source text extractors (pdf.js, pdftotext and pypdf). Commercial systems such as Workday, Greenhouse or Taleo were not tested, and each employer configures its own.
Guides and templates for this resume
Sources, checked 29 October 2026
We opened every page below on that date. Pay, rules and requirements change, so check the source before you rely on a detail.
- GARP: Financial Risk Manager (FRM) Certification (two multiple-choice exams; at least two years of relevant work experience)
More in resume templates by job title.