Resume template · Updated October 2026
Insurance underwriter resume template
Short answer
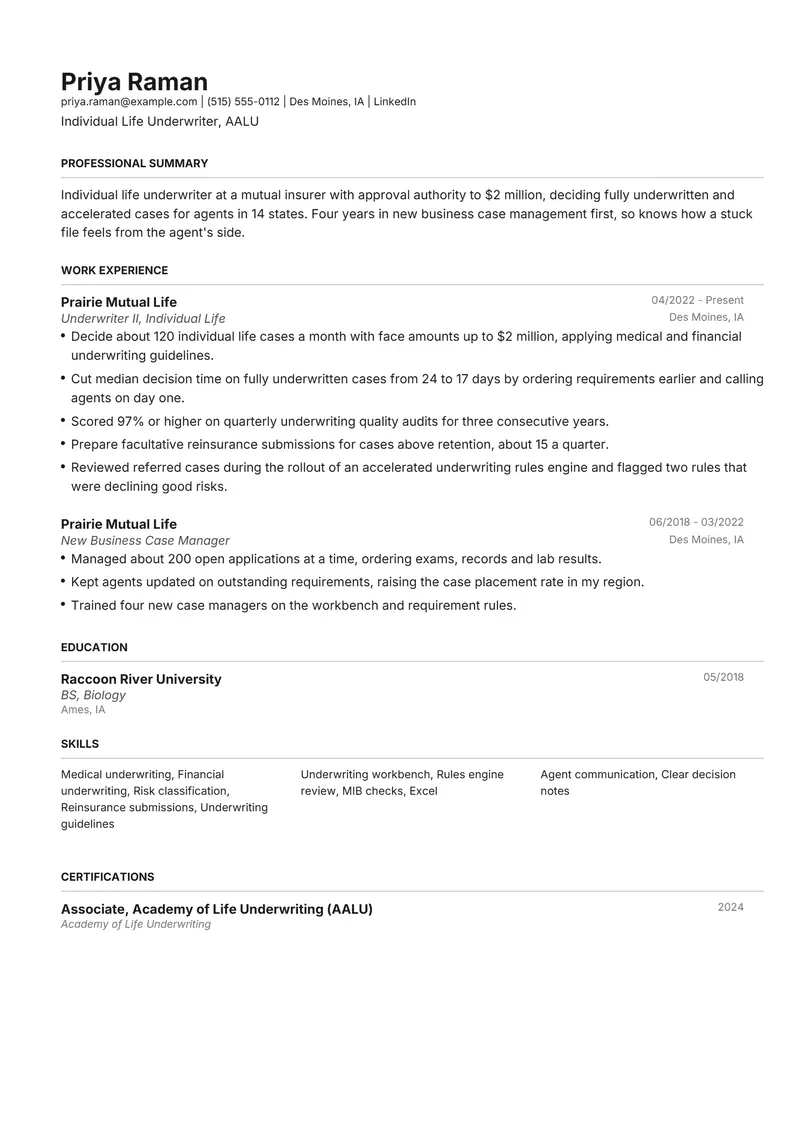
Henrietta suits underwriters, whose employers expect a conventional, careful page: experience comes first and education follows straight after. The fictional sample is an individual life underwriter at a Des Moines mutual insurer who started in new business case management, with a $2 million approval limit, faster decisions, high audit scores, facultative reinsurance cases and the AALU designation on the way to the FALU.
Download the insurance underwriter sample
Priya is a fictional individual life underwriter. Replace every detail with your own before you send it.
The files are made in your browser by Resumity's own exporters, from this sample. The builder opens it as your own resume: click any line to replace it. Free plan, no watermark.
Why Henrietta suits an insurance underwriter resume
Henrietta is the classic business layout of the seven: left-aligned name, black and grey, experience directly under the summary and education after it. Underwriting managers read for authority level, case mix and audit quality, and a plain, orderly page signals the same care they want in your decisions.
Second choice: Meridian. Meridian prints skills before experience, useful for underwriters moving into data-heavy roles such as pricing support or automated underwriting rules.
What goes in each section, in Henrietta's order
Henrietta prints its sections in a fixed order, the same in the PDF and the Word file. Here is that order for this sample, and what to put in each section.
- Professional Summary. Name your line (individual life, disability, group benefits, personal or commercial property and casualty, specialty), your authority level and the distribution you serve (agents, brokers, direct). An underwriter's authority limit tells a hiring manager more than years of experience alone.
- Work Experience. Give volume, authority and quality: cases decided a month, face amounts or premium written, turnaround time, placement or hit ratios, audit scores, and loss ratio where you are accountable for one. Add one bullet on a complex case or a rule you helped write.
- Education. Henrietta prints education straight after the jobs. Life underwriters often come from science, nursing or business degrees; P&C underwriters from business, finance or economics. One line each.
- Skills. The grid shows no labels, so start with underwriting knowledge (medical impairments, financial underwriting, risk classification, or for P&C, exposure analysis and pricing), then systems (rules engines, workbenches, rating tools), then broker or agent communication.
- Certifications. For life underwriters, FINRA's designation listing shows the FALU requires the ALU Level 2 diploma (AALU), three electives and the ALU 301 exam. P&C underwriters usually list CPCU or associate designations instead. Henrietta prints this near the end, so put the main one in your headline.
The sample resume as text
The same content as the files above, so you can copy a line or compare it with your own.
Priya Raman
Individual Life Underwriter, AALU
Des Moines, IA | priya.raman@example.com | (515) 555-0112 | linkedin.com/in/sample-priya-raman
Individual life underwriter at a mutual insurer with approval authority to $2 million, deciding fully underwritten and accelerated cases for agents in 14 states. Four years in new business case management first, so knows how a stuck file feels from the agent's side.
Experience
Underwriter II, Individual Life, Prairie Mutual Life, Des Moines, IA (04/2022 to Present)
- Decide about 120 individual life cases a month with face amounts up to $2 million, applying medical and financial underwriting guidelines.
- Cut median decision time on fully underwritten cases from 24 to 17 days by ordering requirements earlier and calling agents on day one.
- Scored 97% or higher on quarterly underwriting quality audits for three consecutive years.
- Prepare facultative reinsurance submissions for cases above retention, about 15 a quarter.
- Reviewed referred cases during the rollout of an accelerated underwriting rules engine and flagged two rules that were declining good risks.
New Business Case Manager, Prairie Mutual Life, Des Moines, IA (06/2018 to 03/2022)
- Managed about 200 open applications at a time, ordering exams, records and lab results.
- Kept agents updated on outstanding requirements, raising the case placement rate in my region.
- Trained four new case managers on the workbench and requirement rules.
Education
BS, Biology, Raccoon River University (05/2018)
Certifications
- Associate, Academy of Life Underwriting (AALU), Academy of Life Underwriting (2024)
Skills
Medical underwriting, Financial underwriting, Risk classification, Reinsurance submissions, Underwriting guidelines, Underwriting workbench, Rules engine review, MIB checks, Excel, Agent communication, Clear decision notes
How to make the sample yours
Lead with authority and case mix
Write your approval limit and the cases you handle ("individual life up to $2 million, ages 18 to 70, preferred to table ratings"). It positions you instantly against the posting.
Show speed without risk
Turnaround and placement improve sales; audit scores and mortality or loss results show discipline. Pair one of each so you do not look fast and careless, or careful and slow.
Adapt for property and casualty
Commercial and personal lines underwriters swap medical underwriting for exposures, inspections, pricing, renewal retention, broker relationships and loss ratio on their book. The section order stays the same.
Mention automated underwriting work
Many carriers now route simple cases through rules engines. If you helped write rules, tested them or reviewed referred cases, say so; it shows you can work alongside the tools.
From case management, claims or nursing
New business coordinators, claims examiners and nurses already read applications and medical records. Lead with that file experience and the underwriting training you have completed.
Keywords to keep where they are true
Terms this kind of resume is usually searched for. Use the posting's exact wording, and only for work you have done.
- underwriting
- risk assessment
- risk classification
- approval authority
- individual life insurance
- medical underwriting
- financial underwriting
- reinsurance
- underwriting guidelines
- turnaround time
- audit quality
- automated underwriting
- agent and broker relations
- loss ratio
- FALU
Mistakes to avoid
- Leaving out your authority limit or lines of business.
- Policyholder names or medical details, even anonymised loosely.
- Volume figures with no quality measure next to them.
- Designations shown as earned when you have passed only some exams.
How the sample PDF reads in text extractors
We exported this sample with Resumity's PDF exporter in Chrome on 2026-10-29 and read the file back with three open-source text extractors. This shows whether software that turns a PDF into text can recover it; it is not a test of any commercial applicant tracking system. How we test templates.
| Extractor | Name, email, phone | Headings | Bullets intact |
|---|---|---|---|
| pdf.js 4.10.38 | All found | 5 of 5 | 8 of 8 |
| pdftotext (Xpdf) 4.00 | All found | 5 of 5 | 8 of 8 |
| pypdf 6.13.0 | All found | 5 of 5 | 8 of 8 |
Frequently asked questions
How do I become an insurance underwriter with no underwriting experience?
Start close to the work: underwriting assistant, new business, claims or agency service roles. Show file accuracy, attention to detail and any insurance licence or course, then apply for trainee underwriter programmes.
Should underwriters list their approval authority?
Yes. Authority level and lines of business are the quickest way for a hiring manager to place you, more so than years of experience.
What quality measures belong on an underwriter resume?
Audit scores, referral accuracy, loss ratio or mortality results where you are measured on them, and complaint or reversal rates. Pair them with volume and turnaround figures.
Can a nurse move into life or health underwriting?
Yes. Clinical knowledge helps with medical impairments. Lead with record review and assessment experience, then any underwriting courses, and expect to learn financial underwriting and insurer guidelines.
Is the resume different for commercial underwriting?
The layout is the same; the evidence changes to exposures, pricing, broker relationships, renewal retention and the loss ratio of your book.
Will applicant tracking systems read this Henrietta PDF?
The sample PDF read back with its contact details, all 5 section headings and all 8 bullets intact in three open-source text extractors (pdf.js, pdftotext and pypdf). Commercial systems such as Workday, Greenhouse or Taleo were not tested, and each employer configures its own.
Guides and templates for this resume
Sources, checked 29 October 2026
We opened every page below on that date. Pay, rules and requirements change, so check the source before you rely on a detail.
- FINRA: Professional Designations: FALU (Fellow of the Academy of Life Underwriting, issued by the Academy of Life Underwriting; prerequisite ALU Level 2 Diploma (AALU); three elective courses and the ALU 301 exam; online proctored exam)
More in resume templates by job title.